Teradyne Stock Faces A New Test As Warehouse Robotics Partnership Expands
October 23, 20264 Mins read14
Share
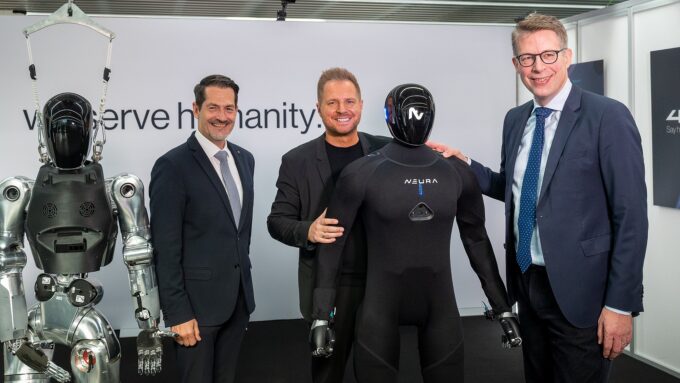
Teradyne Robotics and Sereact announced a partnership that pairs Sereact’s Cortex physical AI platform with Universal Robots’ collaborative arms to automate complex logistics tasks such as returns handling for Zalando’s European fulfillment centers.
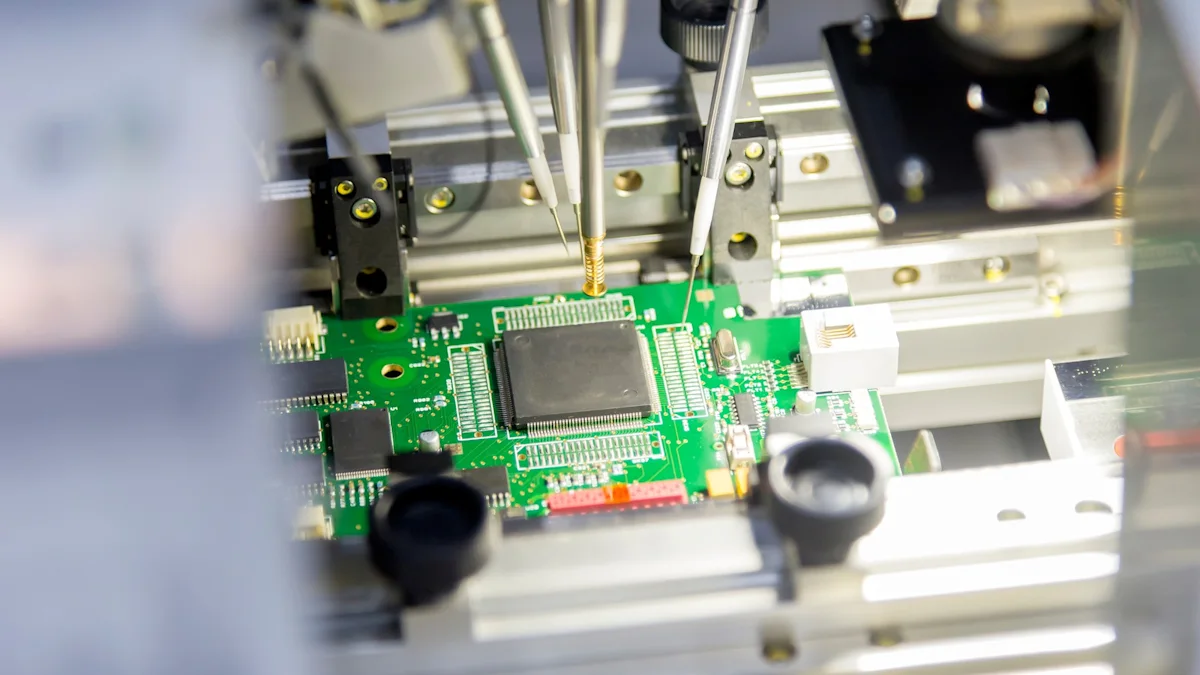
The rollout of hundreds of dual arm UR systems and a live NVIDIA GTC Berlin demo signals that Teradyne is pushing robotics deeper into high volume, unstructured warehouse work that has been hard to automate.
The focus now turns to how Teradyne’s push into AI powered returns automation could influence the broader investment narrative around its robotics business.
Surf 93 robotics and automation stocks to find other automation players pushing AI powered robotics into warehouses and semiconductor production alongside Teradyne.
Teradyne Investment Narrative Recap
To own Teradyne, you need to believe the company can keep turning AI driven semiconductor test demand and physical automation into durable earnings, despite swings in mix and spending cycles. The recent Teradyne Robotics and Sereact update fits that view, but the near term spotlight still sits on the October 27 earnings release and how orders, margins and guidance land after the recent share price pullback.
The biggest immediate operational risk remains gross margin pressure from less compute heavy product mix, memory pricing, and higher R&D and go to market spend that may not convert into the expected future volume. The robotics headlines do not remove that risk. They simply show Teradyne continuing to invest behind AI centric use cases while investors wait for clearer evidence in reported numbers.
The FormFactor collaboration announced on October 12 appears closely connected to the same AI and automation themes that are driving the Sereact partnership. Teradyne is working with FormFactor to advance semiconductor test architectures across high performance compute, advanced packaging, high bandwidth memory and silicon photonics. These areas relate directly to the firm’s largest customers and long term ATE test demand.
For you as a shareholder, that alliance feeds into the main catalyst to watch: Teradyne’s effort to deepen its role at major compute and hyperscaler accounts while supporting more complex devices coming through the fab. It also adds another execution swing factor. Any delay in AI related capital spending or slower than expected adoption of these joint solutions would feed straight back into order visibility, utilization and the earnings trajectory that analysts currently expect.
What The Current Analyst Framework Implies For Teradyne
Teradyne’s analyst model lines up a relatively clear set of hurdles for the next few years. The consensus framework assumes revenue growth of 22.7% a year for three years, profit margins rising from 25.8% to 31.4%, and a future P/E of 37x on 2029 earnings, compared with 54.5x today and 46.9x for the broader US semiconductor peer group. That mix effectively asks investors to accept a strong compounding top line and higher profitability, while also assuming the market will apply a lower earnings multiple to the stock than it does today.
On earnings power, the group forecast calls for profit to move from US$1.2b today to US$2.6b by 2029, with a wide spread between the most optimistic view at US$3.5b and the most cautious at US$1.9b. That US$1.4b step up in the consensus view is what anchors most of the current narrative around Teradyne, including the capital being put into AI test, robotics and partnerships such as FormFactor and Sereact. The expected modest decline in share count of 0.17% per year over the next three years adds a small tailwind to earnings per share if these profit targets are met.
Price targets flow directly from this math. The average analyst mark of US$446.47, with a range from US$350.00 to US$550.00, implies that by 2029 Teradyne would be generating US$8.2b in revenue and US$2.6b in earnings while trading on that 37x P/E multiple and discounted at roughly 11.3% to 11.25%. Against a spot price of US$400.75, the consensus target sits 10.2% higher, which reflects the level of confidence that analyst set has in Teradyne turning its AI test and robotics roadmap into the future income stream embedded in those models.
Teradyne’s narrative projects US$8.2b revenue and US$2.6b earnings by 2029. This would require 22.7% yearly revenue growth and an earnings increase of about US$1.4b from US$1.2b today.
Uncover why Teradyne’s fair value indicates a 45% potential upside to its current price that may not last much longer.
NasdaqGS:TER 1-Year Stock Price Chart
Exploring Other Perspectives
You can read this Teradyne news through a different lens. The most optimistic analysts were already modeling about US$10.5b of revenue and US$3.5b of earnings by 2029, well above consensus. Their catalyst is robotics and AI test scaling faster than expected. This new Sereact partnership might push that story even further, or force a rethink.
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
Looking For More Teradyne-Like Investment Ideas?
If Teradyne’s mix of AI hardware, robotics and semiconductor exposure appeals to you, it can help to line it up against other potential opportunities. The Simply Wall St Screener lets you filter for financial quality, balance sheet strength and income potential so you can build a watchlist that matches your own risk and return preferences.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.




Leave a comment