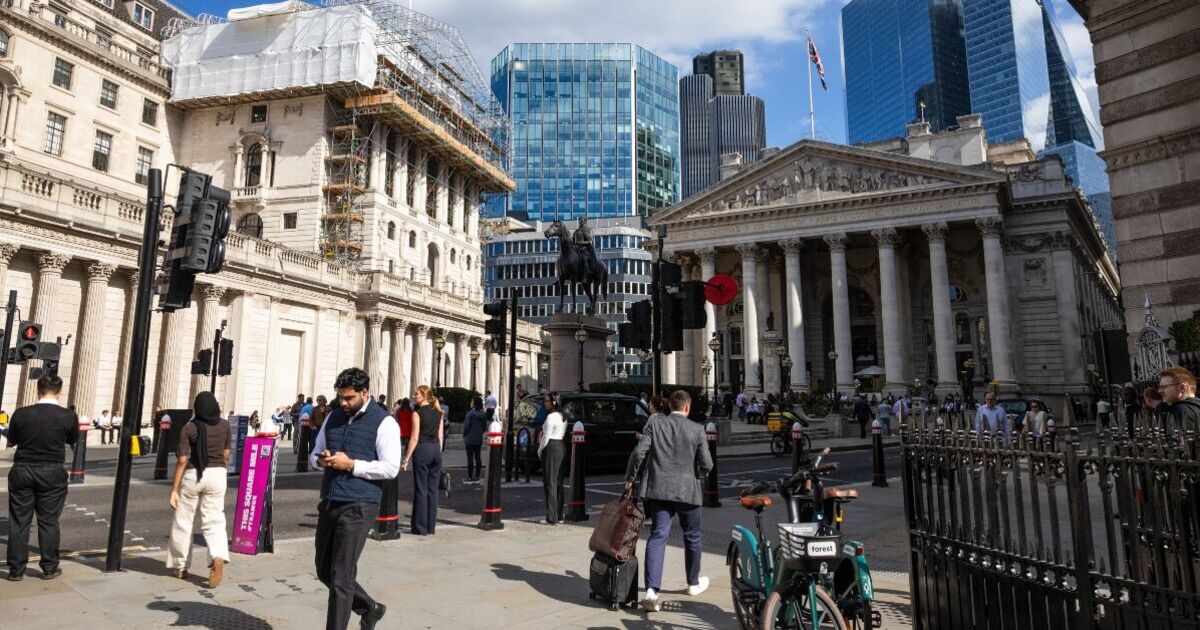

A global bond sell-off has seen UK gilt yields hit 6% for the first time in nearly 30 years (Image: Getty)
A global bond sell-off has pushed UK gilt yields to 6% for the first time in almost 30 years. The yield on UK Government bonds, which is the effective interest rate, reached 6.07% in morning trading on Thursday (October 1). This is the highest level since 1998.
Rising yields on these bonds mean it costs governments more to borrow from financial markets. This piles pressure on Chancellor John Healey as he looks to set out his first Budget at a time of pressure on Britain’s creaking public finances and rising mountain of debt.

The pressure is on John Healey (Image: Getty)
Axel Rudolph, Chief Technical Analyst at IG, said: “Higher yields mean the Government has to pay more to finance its debt, putting further pressure on the public finances and making it harder to balance spending commitments with the need to keep borrowing under control.
“Even the recent fall in oil prices hasn’t provided any lasting relief for bond markets. With yields still rising, the Chancellor faces an increasingly narrow path as he prepares to set out his plans for the economy.”
Neil Wilson, Saxo UK investor strategist, said the “relentless rout in the bond market is sending investors running for cover”.
Worldwide bond market woes spilled over into equities as London’s FTSE 100 Index tumbled by 2%. The FTSE 100 Index shed 209 points to stand at 10397.1 just over an hour after market opening.
Markets were also tumbling across Europe, with the Dax in Germany and France’s Cac 40 both off 1.3%.
Our community members are treated to special offers, promotions, and adverts from us and our partners. You can check out at any time. Read our Privacy Policy

London’s FTSE 100 Index tumbled by 2% (Image: Getty)
This came despite Brent crude prices falling back below $100 (£75.59) a barrel, down 2% at $99.9 (£75.53), on signs that Middle East crude flows are back to pre-Iran war levels.
Government bonds were also slumping across the globe, with the US 10 year bond yield at its highest since 2002.
Susannah Streeter, Chief Investment Strategist at Wealth Club, said: “With debt already high and interest payments eating up a hefty chunk of public finances, sustained yields at these levels could further squeeze the Chancellor’s wiggle room when he sets out his spending plans.”
Jason Hollands, Managing Director of online investment platform Bestinvest, cautioned equity investors not to over-react to short term moves, but focus on the medium to long term.
He added: “Rising market borrowing costs are expected to have a knock-on impact on mortgage rates, so those coming off cheap fixed rate deals over the next six month or so, should engage with their lenders and act to secure a competitive new deal as early as possible as well as review their household budgets in preparation for higher financing costs.”

The rise in borrowing costs is expected to affect mortgage rates (Image: Getty)
Adam French, Head of Consumer Finance at Moneyfactscompare.co.uk, said more remortgage borrowers were considering a variable or tracker mortgage in September.
He added that for someone coming off a very cheap fixed-rate deal, the payment shock can be substantial.
A borrower with a £250,000 mortgage over 25 years who secured a five-year fix at 2.38% in 2021 would have been paying around £1,106 a month.
Remortgaging today onto an average two-year fix at 5.93% would push that to around £1,600 – almost £500 more every month, according to Moneyfacts’ analysis.
Mr French explained that at an average rate of 4.54%, a tracker can soften that immediate hit, adding: “The same mortgage would cost around £1,395 a month, which is roughly £200 less than the average two-year fix.
“But that saving comes with the trade-off that the payment can rise if the Bank of England increases the Base Rate.”
The expert said if Base Rate rises in line with market expectations, then tracker borrowers will see their monthly repayments increase, eating into the savings they make today.


Leave a comment