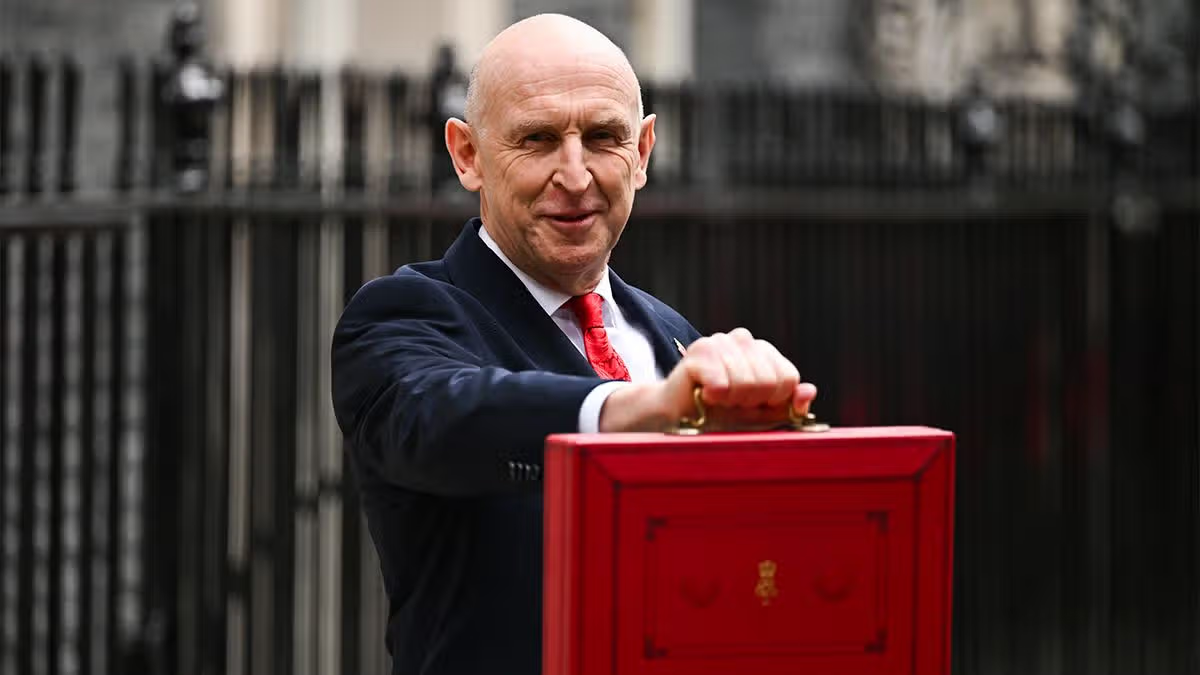
A financial planning expert has explained the changes

Major changes for savers were announced in the Autumn Budget(Image: Getty)
Premium Bonds holders have been urged to think about a key change announced in the Budget. A financial expert says the important update means customers have “more room” to protect their nest egg from being taxed.
Tim Grimsditch, managing director of financial advice group Unbiased, was asked for his thoughts on whether Premium Bonds are still the right home for your savings. One key benefit of Premium Bonds is that any prizes you win in the monthly draw are entirely tax-free. You’d be especially grateful for this rule if you won one of the big prizes, such as £50,000 or £100,000, or one of the £1million jackpots.
Significant change
On the same topic of tax-free savings, a major change was announced in the Autumn Budget that Premium Bonds customers may want to read up on. Mr Grimsditch explained: “The decision to keep the cash ISA allowance at £20,000 is a significant one. It reverses the planned cut to £12,000 for under-65s, which had been due to take effect in April 2027.
Ensure our latest Premium Bonds headlines always appear at the top of your Google Search by making us a Preferred Source. Click here to activate or add us as Preferred Source in your Google search settings.
“Anyone who had started adjusting their savings plans around that lower limit should know the cut is no longer going ahead.” With ISAs, any interest earnings or investment growth within these accounts is tax-free, and you can put in up to £20,000 each tax year, divided however you want between cash ISAs or investments.
There were previous plans to reduce the amount you could put wherever you want to £12,000, with the other £8,000 only to be available for investments, starting in April 2027. But Chancellor John Healey announced in his Budget statement that these changes would not go ahead.
Mr Grimsditch said keeping the full £20,000 allowance keeps options open for savers. He said: “That matters because savers will still be able to put their full £20,000 annual ISA allowance into cash, provided they haven’t used some of it in another type of ISA. With tax on savings interest rising, that gives people more room to protect their interest from tax than they had been expecting.”
If you do have cash savings that attract a tax bill, the tax you pay on your interest earnings will be going up from April 2027. The tax rate is increasing by four percentage points across all tax bands.
Key tax-free rules
So putting this all together with some other rules, these are the key tax-free figures for Premium Bonds savers or those looking at the scheme to think through:
- Premium Bonds – You can hold up to £50,000 in Premium Bonds. Any prizes you win are tax-free. The odds of winning for each £1 Bond are currently 21,000 to one, with the annual prize fund rate at 4.35 per cent
- £20,000 ISA allowance – You can put away up to £20,000 each tax year into ISAs, splitting this however you choose between cash or investments / stocks and shares
- Personal savings allowance – Aside from your ISA allowance, you can earn up to a certain amount each tax year in interest tax-free. This is £1,000 for basic rate taxpayers, £500 for higher rate taxpayers, zero allowance for additional rate taxpayers
- Interest tax increase – The rate you pay on any taxable interest earnings is increasing by four percentage points from April 2027. So for basic rate taxpayers, it will go up to 24 per cent, for those on the higher rate, up to 44 per cent, and for additional rate taxpayers, up to 49 per cent.
For people thinking of buying Bonds, Mr Grimsditch said: “Before moving money into Premium Bonds, look at how much of your ISA allowance you have available, whether your interest exceeds your tax-free allowances and whether you need your savings to provide a regular income. The appeal of a possible prize is understandable, but the right home for your money depends on what you need it to do.”
His comments come after investment platform AJ Bell recently spoke about some important changes coming up for Premium Bonds savers to think about. Mr Grimsditch spoke about when Premium Bonds can be a good choice.
When Premium Bonds are a good choice
He said: “Premium Bonds become more interesting for people who have already used their £20,000 ISA allowance and exhausted their personal savings allowance, or have no allowance because they are additional-rate taxpayers. For that narrower group, tax-free prizes and the security of Government-backed savings can be appealing.
“But protecting your original money is different from earning a reliable return, and Premium Bonds do not guarantee any earnings.”
But the reality is for many savers, you will likely get a better return elsewhere. Mr Grimsditch said: “Higher savings tax makes tax-free options more valuable, but for most savers facing a tax bill on their interest, a competitive cash ISA is likely to be the better starting point. It pays interest you can plan around, whereas Premium Bonds offer the chance of a prize. Both are tax-free, but you could hold Premium Bonds and win nothing.”


Leave a comment