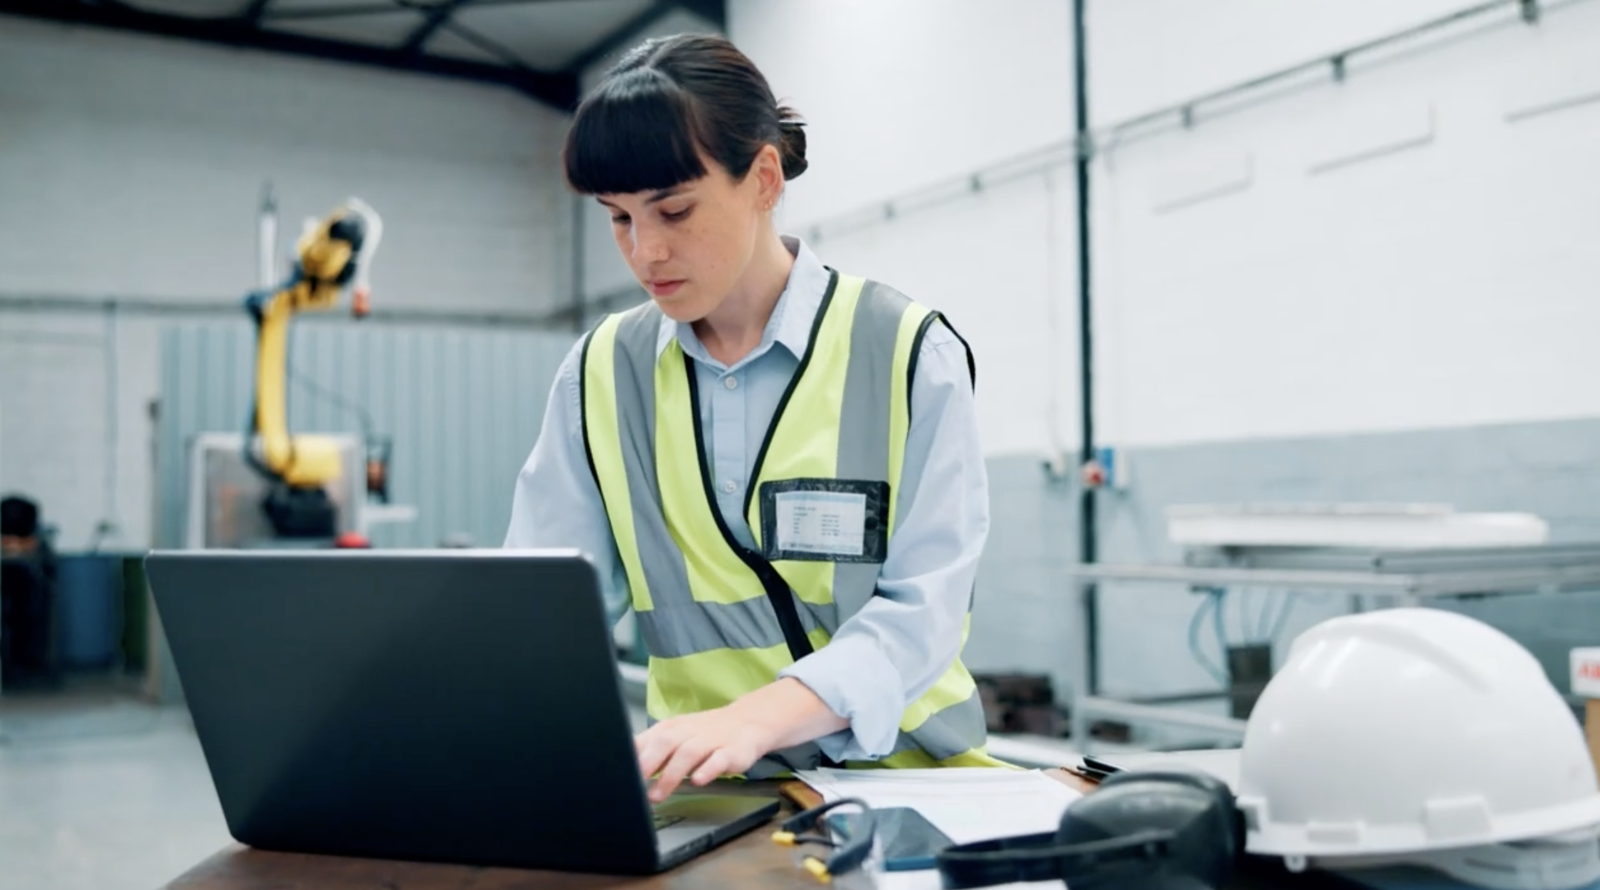
North American manufacturers placed orders for 10,989 industrial robots valued at $723.5 million in the third quarter of 2026 — a 24.8% increase in units and a 26.1% jump in value over the same period last year, per Q3 2026 robot order data from the Association for Advancing Automation (A3) — with a structural shift buried inside that headline number that signals something more consequential than a quarterly rebound. The fastest-growing category, collaborative robots (cobots), recorded cobot segment Q3 2026 growth of 56% year-over-year in units and now accounts for 16.7% of all North American robot orders, driven not by a general appetite for automation but by two specific industries executing a once-in-a-generation manufacturing buildout that needs exactly what cobots uniquely provide: a robot that can work alongside humans in a clean, uncaged environment without fixed safety infrastructure.
Data released by A3 around October 30 showed that semiconductor fabrication facilities — the cleanrooms being constructed under the CHIPS and Science Act across Arizona, Ohio, New York, and Texas — saw Q3 robot orders up 97.6% compared to Q3 2025. The life sciences sector, which includes pharmaceutical manufacturing plants reshoring drug production under Trump-era executive orders and the FDA’s PreCheck Pilot Program that launched in February, showed cobots capturing 43.8% of year-to-date robot orders in that vertical, with semiconductors accounting for 36.9%. Alex Shikany, executive vice president at A3, described Q3 as evidence of “a robotics market that is becoming increasingly diversified across industries and applications” — an indicator of structural momentum rather than a single-sector order wave.
Why Cobots, Not Conventional Robots, Win Cleanrooms
The 56% cobot growth figure is not separable from the physical requirements of the facilities driving it. Semiconductor fabs and pharmaceutical manufacturing plants operate under strict contamination standards — ISO 14644-1 Class 5 through Class 8 environments where every surface, seal, and structural element that can shed particles is a liability. The safety cages that traditional industrial robots legally require under OSHA robot safety caging standards do exactly that: their metal frame structures, joints, and access panels introduce particle-shedding surfaces into environments built to eliminate them.
Cobots solve this problem through a safety architecture called Power-and-Force Limiting, or PFL — the dominant mode defined under ISO/TS 15066:2016 and updated in the ISO 10218-2:2025 collaborative safety standard. Where a traditional industrial robot must be physically isolated because it has no mechanism to detect human contact, a PFL-compliant cobot uses joint torque sensors at every axis to continuously monitor the forces being applied to its arm. Using real-time kinetic energy calculations (E = ½mv²), the control system ensures that any contact with a human worker keeps the applied force below the ISO 10218-2:2025 biomechanical force threshold — 80 to 150 Newtons depending on body region — and decelerates the arm to a full stop within roughly 100 to 300 milliseconds, faster than a human reflex arc.
The practical consequence for a semiconductor fab operator or a pharmaceutical plant manager is straightforward: no cage means no dedicated cage footprint in a cleanroom where floor space costs hundreds of dollars per square foot to build and certify. It also means no fixed safety zone that must be de-energized for tooling changes between semiconductor lot runs or pharmaceutical batch productions — the rapid reconfigurability that makes cobots economically viable in the high-mix, variable-volume environments that characterize both industries, a point reinforced by cage-free cobot cleanroom deployment case data published by A3.
Typical 2026 commercial cobots operate with payloads of 3 to 30 kilograms (6.6 to 66 pounds) and reach distances of 600 to 1,800 millimeters (24 to 71 inches) — sufficient for semiconductor wafer cassette handling, pharmaceutical vial and blister-pack assembly, and PCB component placement. Most now offer no-code cobot programming interface requiring no specialist robotics knowledge, a meaningful advantage for reshored facilities that cannot draw from the deep skilled-robot-programming talent pools available in established offshore manufacturing regions.
Chipmakers and Drug Manufacturers Lead a Reshoring Buildout
The semiconductor sector’s 97.6% robot-order increase in Q3 reflects an infrastructure commitment that precedes the quarter by years. The CHIPS Act $52.7 billion funding for domestic semiconductor manufacturing and R&D, signed in 2022, underpins fab construction timelines — TSMC in Arizona, Intel in Ohio, Micron in Idaho and New York, Samsung in Texas — now entering the equipment installation phase where automation orders accelerate. Because these facilities are built to multi-decade operational lifespans with cleanroom specifications set at construction, the automation infrastructure decisions made now establish ordering patterns that will persist through the end of the decade.
The pharmaceutical sector’s automation investment follows a different but equally durable policy trajectory. A May 2025 executive order directed federal agencies to support domestic drug manufacturing as a national security priority, and the FDA’s PreCheck Pilot Program — launched February 1, 2026 — created expedited inspection pathways for U.S.-based pharmaceutical manufacturers, reducing the regulatory overhead that had previously made offshore production more attractive. The investment response has been substantial: more than $270 billion in announced U.S.-based pharmaceutical manufacturing investments have been committed since 2025, with GSK committing $30 billion, Johnson & Johnson pledging $55 billion, and Eli Lilly committing $27 billion to domestic facilities. Cobots captured a life sciences 43.8% YTD share of year-to-date robot orders in life sciences as of Q3, reflecting how consistently pharma plant designers are choosing cage-free automation for the packaging, dispensing, and handling tasks that require both precision and rapid retooling between drug lines.
Broader Q3 Numbers: Automotive Stabilizes as Food Contracts
Outside the two headline sectors, the Q3 data showed an automotive market finding its floor after a difficult year. Automotive OEM Q3 2026 orders showed 7.5% unit growth in Q3 — a positive turn for a sector that remains down 17% in year-to-date units compared to 2025. Automotive components Q3 2026 growth reached 90.4% as Tier 1 and Tier 2 suppliers accelerated investments in response to reshoring-driven demand from automakers building or expanding North American production lines.
Not every sector participated. The food sector Q3 2026 decline of 23.7% year-over-year continued a pattern of caution in consumer-facing industries where input cost volatility and uncertain consumer spending have slowed capital investment decisions. The plastics rubber Q3 67.7% growth suggested that the same reshoring dynamics affecting pharma packaging — where domestic production of containers, closures, and delivery devices is growing alongside drug manufacturing — is generating automation demand in adjacent material categories.
The macroeconomic backdrop supported the acceleration. The Institute for Supply Management’s Manufacturing PMI reached 54.5 in September 2026 — its ninth consecutive month above 50, indicating expansion — while Federal Reserve data showed manufacturing output rising 0.3% in September. Year-to-date through Q3, A3 YTD 2026 robot orders totaled 28,984 robots valued at $1.89 billion, representing 9.6% unit and 13.3% value growth over the same period in 2025.
How Large Is the Cobot Market and Where Is It Heading
The International Federation of Robotics reported 64,500 collaborative robots installed globally in 2024, representing approximately 11.9% of total industrial robot installations worldwide — up from roughly 2.8% in 2017, as reported in the International Federation of Robotics’ World Robotics 2025 report. The North American market is growing significantly faster than the global average, which Mordor North American cobot market analysis attributes to the concentrated effect of the CHIPS Act fab buildout and the pharmaceutical reshoring investment wave on a geography with relatively thin existing robot density compared to South Korea, Japan, and Germany.
Mordor Intelligence projects the North American collaborative robot market at approximately $2.56 billion in 2025, growing to $3.23 billion in 2026, and reaching the cobot market $10.26 billion forecast by 2031 at a compound annual growth rate of 26.05%. Interact Analysis projects a 17.3% compound annual growth rate for the global cobot segment through 2030, compared to 6.7% for the overall industrial robot market — a gap it attributes largely to the same cleanroom and pharmaceutical deployment dynamics driving Q3’s numbers.
The ISO 10218-2:2025 collaborative application update, which replaced the term “cobot” with “collaborative application,” broadens the commercial significance of PFL safety architecture: because the standard defines collaborative-mode safety as a function of system design rather than hardware category, higher-payload robot arms can now achieve cage-free certification through the right safety integration, expanding the addressable market for cage-free industrial automation beyond the traditional 3-to-30-kilogram cobot segment.
A3 Safety Conference Opens Monday in Detroit
The A3 International Robot Safety Conference opens Monday, November 3, running through November 5, where collaborative robot safety standards and the evolving requirements of cage-free industrial deployments will be among the featured topics. The conference follows directly on the Q3 data release, and discussions around ISO 10218-2:2025 implementation are expected to reflect the semiconductor and pharmaceutical deployment questions now driving the fastest-growing segment of the North American robot market.
A3’s next industry events include the A3 Business Forum in Orlando in January 2027 and Automate 2027 in May 2027, where Q4 2026 order data — expected to show whether the semiconductor and pharmaceutical buildout momentum continued through the end of the year — will be a central data point for equipment manufacturers, system integrators, and automation buyers planning their 2027 capital allocations.
Frequently Asked Questions
What makes collaborative robots suitable for semiconductor and pharmaceutical cleanrooms when traditional industrial robots are not?
Collaborative robots use a safety mechanism called Power-and-Force Limiting (PFL) — now standardized under ISO 10218-2:2025 PFL safety requirements — which uses joint torque sensors to stop the robot on unexpected human contact without requiring a physical safety cage. In ISO 14644-1 cleanroom environments — the particle-controlled spaces required for semiconductor wafer fabrication and pharmaceutical manufacturing — safety cages introduce contamination surfaces, consume expensive certified floor space, and cannot be rapidly reconfigured between production runs. Cobots eliminate the cage, operate in cleanroom-certified spaces without fixed safety infrastructure, and can be retooled between lot runs without de-energizing a safety zone. Traditional industrial robots, which operate at speeds and forces incompatible with unprotected human presence, require caging that cleanroom environments cannot easily accommodate.
Why are North American robot orders accelerating in 2026 when they were slow in the first half of the year?
Year-to-date growth through Q2 2026 was approximately 2% in units — slow by historical standards. Q3’s 24.8% jump reflects two specific infrastructure timelines converging: semiconductor fabs funded by the CHIPS Act semiconductor fab investment (signed 2022) are now entering the equipment installation phase of multi-year construction projects, generating concentrated automation orders, while pharmaceutical manufacturers are acting on more than $270 billion in domestic investment commitments made since the Trump administration’s May 2025 executive order prioritizing domestic drug production. Both represent multi-year buildout pipelines, not single-quarter demand spikes, which is why industry analysts project sustained cobot growth through 2031.
Which industries are not participating in the robot order growth, and why?
Food and consumer goods manufacturing declined 23.7% in Q3 2026 year-over-year, and automotive original equipment manufacturers remain down 17% on a year-to-date basis despite a positive Q3. In both cases, the drag reflects demand-side uncertainty rather than a structural shift away from automation: food and consumer goods manufacturers face input cost volatility and cautious consumer spending that slows capital investment decisions, while automotive OEMs have been working through inventory normalization and are only beginning to commit to the next wave of facility investments associated with EV platform transitions. The overall market’s growth is being carried by the semiconductor and pharmaceutical sectors, which are operating on policy-mandated investment timelines that are relatively insulated from near-term consumer demand cycles, as reflected in Q3 2026 sector order breakdown data from A3.
What does the ISO 10218-2:2025 standard update mean for industrial robot buyers?
The 2025 revision replaced the term “cobot” — which had informally come to mean a specific class of low-payload, cage-free robots — with “collaborative application,” shifting the definition from hardware category to system design outcome. Under ISO 10218-2:2025 higher payload certification, any robot system that achieves power-and-force limiting safety within the standard’s biomechanical thresholds qualifies as a collaborative application, regardless of the robot’s payload capacity. This broadens the market: higher-payload robots that previously required caging can now be certified for cage-free operation through appropriate safety integration, expanding the range of tasks addressable by cage-free automation beyond the 3-to-30-kilogram cobot segment that currently leads the North American market.


Leave a comment