With six days to go until chancellor John Healey delivers his Autumn Budget statement on 28 October, practice teams advising corporate clients face a familiar dilemma. Clients finalising their 2027 commercial budgets and investment cycles want firm tax numbers. Yet, after two years of shifting fiscal policy, corporate directors are understandably sceptical when advisers tell them that the rules are “settled.”
The government attempted to eliminate this uncertainty with its Corporate Tax Roadmap, promising a predictable framework for the remainder of this parliament. The intention was sound: give businesses the confidence to commit capital without fearing sudden mid-year tax spikes.
However, translating a political roadmap into actual practice requires sorting statutory guarantees from operational realities. For advisers preparing clients for 2027 year-ends, the current corporate tax landscape splits into three distinct categories: what is genuinely locked in, what has already been tweaked under fiscal pressure, and what remains vulnerable when the chancellor opens his red box on 28 October.
1. The Core Guarantees: What Is Locked In
For all the speculation surrounding the Treasury’s fiscal gap, the headline framework for corporate profits remains the most stable part of the UK tax system. According to the government’s roadmap, the baseline statutory parameters committed to for this parliament are firm:
-
The 25% Main Rate Cap: The headline corporation tax rate for non-ring-fenced profits above £250,000 is capped at 25% for the duration of this parliament. The UK continues to maintain the lowest headline rate in the G7.
-
The 19% Small Profits Rate & Marginal Relief: The 19% rate for profits up to £50,000 remains intact, along with the marginal relief taper up to £250,000. For mid-sized corporate clients sitting in the £50,000 to £250,000 bracket, the effective marginal rate of 26.5% continues to apply.
-
Permanent Full Expensing & the £1m AIA: Plant and machinery capital allowances retain their statutory backing. Main rate assets qualify for 100% first-year write-offs, special rate assets retain a 50% first-year allowance, and the Annual Investment Allowance (AIA) remains fixed at £1m for all qualifying businesses.
-
R&D Relief Generosity: Following the merger of the RDEC and SME schemes into a single merged R&D scheme, the baseline relief rates are settled, providing certainty for qualifying expenditure.
For corporate clients planning main-plant equipment upgrades or property fit-outs for the 2027 financial year, these core relief mechanisms can be safely modelled in capital expenditure forecasts today.
2. The Recent Shifts: What Has Already Moved
While headline rates have held firm, the ground beneath corporate tax calculations has already shifted significantly. Advisers should remind clients that “rate stability” does not mean tax bills have stayed static. Recent fiscal measures have squeezed cash tax positions by slowing down writing-down allowances and raising payroll overheads long before profit is assessed.
Slowing Down Capital Allowances
The clearest example of relief becoming less generous while headline rates remain unchanged is the reduction in writing-down allowances (WDAs). The main rate WDA for plant and machinery was reduced from 18% to 14% for corporation tax, taking effect from 1 April 2026. While the special rate pool remains unchanged at 6%, the WDA cut means relief on non-full-expensing assets is written off far more slowly over time.
To partly offset this, a 40% first-year allowance (FYA) took effect from 1 January 2026 for main rate assets, including qualifying plant or machinery purchased for leasing (excluding second-hand assets, cars, and assets leased overseas). For corporate finance teams, modelling 2027 capital expenditure now requires a far more granular split between full expensing, the 40% FYA, and the slower 14% WDA pool.
Escalating Employer Overhead Strain
Corporate cash flows face additional pressure before corporation tax even comes into play due to substantial increases in employer National Insurance contributions (NICs):
-
Higher Employer NIC Rate: The employer NIC rate rose from 13.8% to 15%.
-
Lower Secondary Threshold: The secondary threshold where employer NICs become payable was dropped sharply from £9,100 to £5,000 per employee, with the threshold freeze extended until April 2031.
These payroll changes mean that even with a frozen headline 25% corporation tax rate, the total tax take on UK businesses has crept upward, directly reducing pre-tax profit margins.
3. The Open Questions for 28 October
The primary risk for corporate clients on Budget day does not lie in a sudden jump to a 26% headline rate. Instead, it lies in targeted adjustments designed to raise revenue without technically breaking manifesto commitments on headline rates.
With the government committed to raising £10 billion in additional revenue by 2029–30 through closing the tax gap, practice leaders should monitor three specific areas when the Red Book lands:
-
International & Cross-Border Rules: The roadmap explicitly leaves international rules open to evolution. Practice teams should watch for draft legislation stemming from consultations on transfer pricing, permanent establishments, and Diverted Profits Tax reform.
-
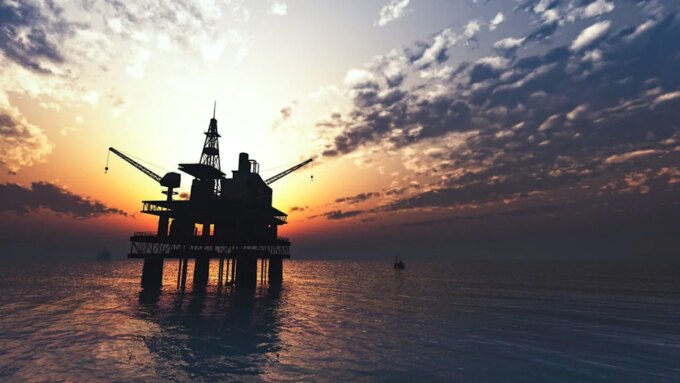
Sector-Specific Levies: While general corporate profits are capped at 25%, sector-specific taxes remain open to revision. The Energy Profits Levy is scheduled to run until 2030, but adjustments to rates or investment allowances could appear on 28 October.
-
HMRC Enforcement Focus: Further compliance measures are likely given the £10bn target. Practice teams should prepare for tightened enforcement, as close company loans to participators (section 455 tax) and R&D claims remain a known HMRC focus.
Guiding Corporate Boards Through the Noise
When advising corporate boards over the coming days, the most valuable service an accountancy firm can offer is distinguishing between political headline noise and actionable tax engineering.
Tell your corporate directors to leave headline rate anxiety aside. Instead, focus their pre-Budget prep on auditing capital expenditure schedules to maximise full expensing and the 40% FYA, reviewing payroll overheads under the tighter NIC threshold, and ensuring international group documentation meets HMRC’s strict standards.
The Corporate Tax Roadmap provides a reliable skeleton for 2027 planning, but navigating the real cost of corporate tax requires looking beyond the headline 25% rate.



Leave a comment