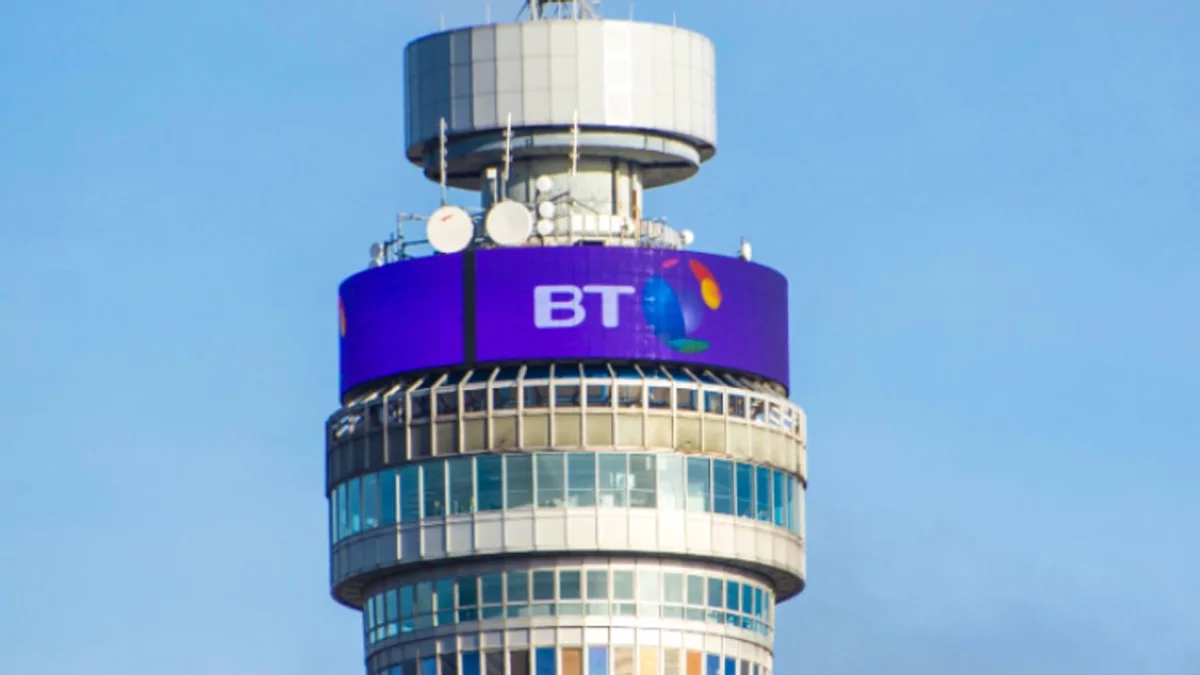

JP Morgan retained its ‘overweight’ rating on BT Group PLC (LSE:BT.A), the British telecom operator, after its planned acquisition of TalkTalk, saying the deal could mark the start of wider UK sector consolidation.
Lead analyst Akhil Dattani said the £400 million deal supports the bank’s long-standing view that several highly leveraged telecoms operators have unsustainable capital structures.
The all-in acquisition cost includes about £100 million owed by TalkTalk to BT’s Openreach infrastructure arm and roughly £60 million of anticipated trading losses through the end of the year.
JP Morgan estimates the transaction could represent about twice synergised operating free cash flow, although it highlighted significant execution risks.
The bank also said BT’s guidance for March 2027 estimated excess free cash flow remains intact, with the potential shortfall from TalkTalk offset because it is already captured within the overall transaction cost.
BT is acting as a buyer of last resort after TalkTalk failed to secure a buyer and entered administration, while the Department for Culture, Media and Sport issued a Public Interest Intervention Notice over concerns about the consequences of its failure.
JP Morgan does not expect significant regulatory risks because TalkTalk has about 5% of the UK retail broadband market, while BT would have a 36% share after the deal, broadly in line with the European incumbent average.
The bank acknowledged that the accounting treatment would be complex but said its initial modelling indicates the transaction should be highly single-digit accretive to BT’s normalised free cash flow over the medium term.
The deal could also help Openreach, as TalkTalk has been a major source of customer line losses, with BT expected to stabilise the customer base after the acquisition.
JP Morgan said the transaction also removes the risk that an infrastructure-focused buyer could have acquired TalkTalk and migrated its customers away from BT’s network.
The bank expects the deal to be the first in a wave of UK telecoms consolidation, which could improve market conditions and help BT earn a fair return on its long-term fibre investments.


Leave a comment