They require a comprehensive, reliable financial ecosystem. This is precisely the direction in which the UK’s fintech sector is evolving, setting new standards for cross-border commerce.
A significant development for the industry came with the official announcement of a major strategic partnership between UK-based fintech company Sends and international payment network UnionPay International (UPI). For Sends, which was recently named in the prestigious Payments Power 50 2026, recognising leading players in the global payments industry, the partnership represents a major strategic milestone. The agreement is set to significantly enhance the company’s payment capabilities across both card issuing and acquiring.
“Payments are becoming increasingly global, while customers and businesses expect the experience itself to remain simple. Our cooperation with UnionPay International is an important step towards building infrastructure that brings these two realities together,” said Alena Shevtsova, CEO of Sends. “By developing both issuing and acquiring capabilities, we are giving customers greater freedom of choice while enabling merchants to reach a vast international audience.”
Why Should Fintech Companies Bring Card Issuing and Acquiring Together?
Traditionally, banks have built their services around separate financial products, while many emerging fintech platforms initially focused on a single area, whether foreign exchange, money transfers or payment acceptance. Today, however, market expectations have shifted.
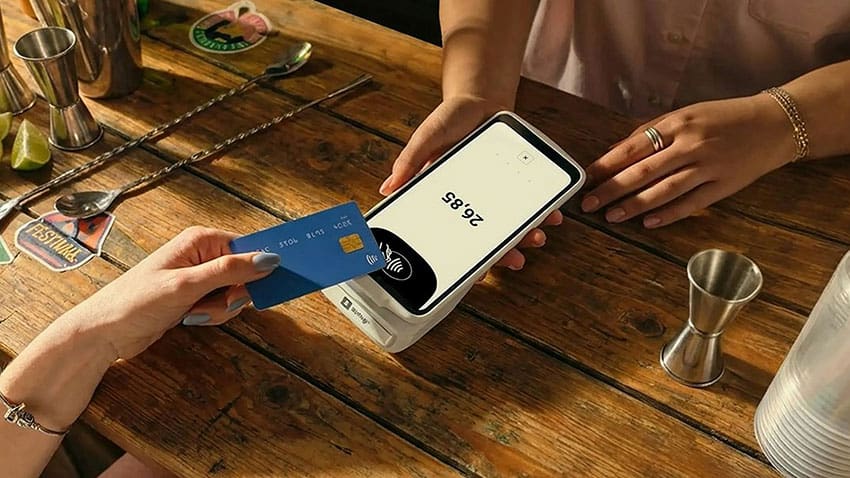
Companies operating internationally increasingly want to manage their financial flows through a unified infrastructure. Card issuing and acquiring have traditionally served different purposes: issuing enables businesses and individuals to make payments and manage their funds, while acquiring allows merchants to accept payments from customers.
Bringing both sides of the transaction, card issuing and payment acceptance, together within a single digital ecosystem creates significant synergies. Rather than simply processing individual transactions, businesses can manage incoming funds, make international payments and handle payouts through interconnected services.
For Sends, this integration is central to its strategy. The company is developing an infrastructure that supports customers throughout the movement of funds, reducing operational complexity at every stage.
“We are building more than just a card or payment product. We are developing financial infrastructure that supports customers at different stages of their financial operations. Our aim is to reduce the operational complexity of international business and make financial processes more predictable, transparent and easier to scale,” said Alena Shevtsova.
The Asian Opportunity: Practical Benefits for European Businesses
Asia remains one of the driving forces behind global trade, yet European companies looking to expand into Asian markets often face barriers related to payment infrastructure. Sends’ partnership with UnionPay International aims to overcome these obstacles, providing access to a vast international customer base and facilitating cross-border commerce.
Industry experts identify several key areas where integration with UPI could make a significant difference.
First, European e-commerce. British and continental European online retailers selling premium products to Asian customers risk losing a substantial share of potential revenue due to payment limitations. Even when international delivery is available, businesses may miss out on sales if customers cannot use their preferred payment methods. Integrating UnionPay into acquiring services will broaden the range of payment options available to shoppers, potentially improving conversion rates among customers who use UnionPay cards.
By expanding payment acceptance to include UnionPay, merchants can remove a significant barrier at checkout, creating opportunities to increase completed transactions and improve overall sales conversion.
Second, the travel and hospitality industry. Hotels, tour operators and premium service providers across the UK and Europe cater to a diverse international clientele, including a significant number of travellers from Asia. The ability to accept UnionPay payments allows these businesses to accommodate customers’ preferred payment methods, providing a more convenient experience without requiring them to seek alternative ways to pay.
Third, international entrepreneurs and businesses. For companies and individuals operating across European and Asian markets, UnionPay cards offer a practical and versatile solution for everyday business expenses and financial transactions, particularly in countries and at merchants where the network has a strong presence.
Given UnionPay’s extensive global reach, the opportunities extend well beyond China to include rapidly developing markets across Asia. Its established international acceptance network creates additional possibilities for businesses seeking to expand their operations and serve customers across multiple regions.
For Sends, the partnership represents an opportunity to help European businesses broaden their international customer base while giving users access to additional payment solutions. In this context, UnionPay serves as another bridge connecting European financial infrastructure with international commerce.
Security Architecture: Real-Time Risk Management
As cross-border operations expand, security inevitably becomes a top priority. As a UK-based company operating under the regulatory oversight of the Financial Conduct Authority (FCA), Sends places strong emphasis on compliance, including rigorous Know Your Customer (KYC) and Anti-Money Laundering (AML) procedures.
The platform also incorporates security measures directly into its financial products. For example, Sends cards have dedicated balances that are kept separate from the primary account of the business or individual user. This allows customers to set strict spending limits and significantly reduce potential exposure if card details are compromised. By managing an integrated financial ecosystem, the platform can also leverage transaction analytics to identify unusual activity promptly and detect potential fraud at an early stage.
Today, the Sends product ecosystem encompasses personal and business accounts, international money transfers, foreign exchange services, payment cards, acquiring and payout solutions.
For entrepreneurs, this means being able to manage multiple financial needs through a single provider rather than maintaining separate relationships with numerous financial service companies. This is particularly valuable for international businesses, whose financial operations rarely involve just one country or currency.
“Today, customers assess the quality of the digital experience, speed of service, transparency of terms, reliability of infrastructure and the ability of their financial partner to support their growth. We are not seeking to compete solely on the number of features we offer. Our goal is to make complex financial infrastructure simple and accessible to customers,” said Alena Shevtsova.
Looking Ahead: An Ecosystem-Driven Approach
Sends does not view its partnership with UnionPay International as the introduction of a standalone feature. Instead, it sees the collaboration as a long-term foundation for three strategic objectives: expanding its geographical reach, accelerating the growth of its acquiring business and further strengthening its position as a comprehensive financial platform.
As Alena Shevtsova, CEO of Sends, points out, modern businesses increasingly expect simplicity from their financial services, even as the global business environment becomes more complex. By continuing to develop its product ecosystem, from streamlined UK account opening and integrated travel eSIM services to international card programmes, Sends aims to become more than just a financial service provider. Its ambition is to establish itself as a trusted infrastructure partner for international businesses, supporting their growth and expansion across global markets.



Leave a comment