The relentless rise in government bond yields – the cost of countries’ borrowing and the pressure that puts on their finances – has become headline news. A crisis in which governments will be forced to slash public spending to reduce their deficits and stop the relentless rise in ratios of government debt to GDP is widely predicted.
But it is rare for crises to be widely predicted, and, if they are, they never unfold as expected. In the popular narrative, “the bond vigilantes”, a term coined by Ed Yardeni in the 1980s to describe investors who keep governments in check when deficits, debt and inflation threaten, will boycott government bond markets. This will force yields higher (reflecting falling prices) and trigger a fiscal crisis that forces governments to act.
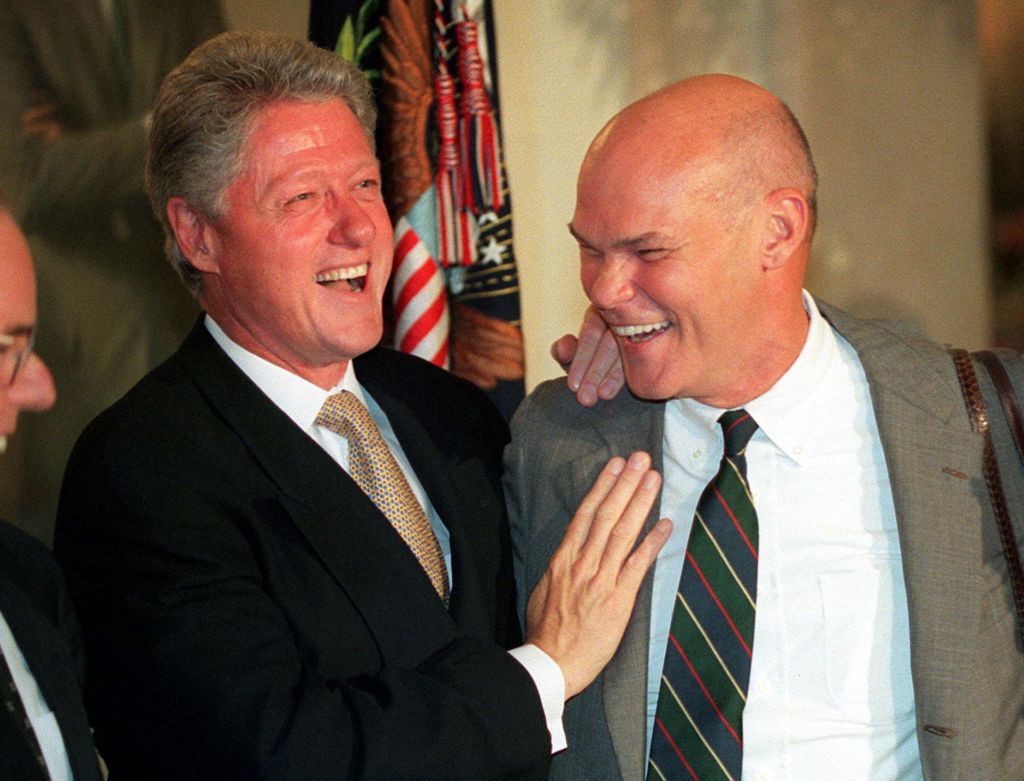
“I used to think that if there was reincarnation, I wanted to come back as the President or the Pope… But now I would like to come back as the bond market. You can intimidate everyone”, quipped James Carville, the chief political adviser to Bill Clinton. In those days, bond investors had been battered by decades of persistent inflation and rising government bond yields.
Try 6 free issues of MoneyWeek today
Get unparalleled financial insight, analysis and expert opinion you can profit from.
Start your trial
Sign up for MoneyWeek’s free twice-daily newsletter.
Join more than 165,000 subscribers and keep yourself informed with latest financial news, insights and expert analysis to help you understand what really matters when it comes to your finances.
Join more than 165,000 subscribers and keep yourself informed with latest financial news, insights and expert analysis to help you understand what really matters when it comes to your finances.
Today, they are worried by four factors: rising inflation, led by rising oil and gas prices; the inability or refusal of governments to control budget deficits; escalating levels of national debt; and the impact of inflation, deficits and rising bond yields on the economy and markets, threatening a spiral of bond yields reminiscent of the 1970s.
In fact, oil prices in real terms are little higher than their average this century ($95 a barrel for Brent). The rise in petrol prices has been exacerbated by a shortage of refining capacity thanks not just to the Middle Eastern war but to the destruction of refineries in Russia and Ukraine. Wholesale natural gas prices have risen much more than the oil price, but new supplies of liquefied natural gas (LNG) are coming on-stream.
Oil exports are increasingly circumventing the blockade of the Strait of Hormuz which, in due course, is likely to be lifted, enabling LNG exports to resume. The best cure for higher oil and gas prices is higher prices, which encourage increased supply and discourage demand.
Why government bond yields have risen
Higher energy prices have pushed up the rate of inflation but without a wage-price spiral, of which there is no sign even in the UK, inflation will soon drop down again. Wage pressures are muted in the UK’s private sector and everywhere in the US and Europe. In the US, strong productivity growth is keeping labour costs down. The difference between the yields on conventional and index-linked government bonds shows that expectations of inflation for the years ahead remain moderate, and the inflation data supports this.
So why have bond yields risen? Real interest rates were negative between 2019 and 2022 but have now risen above 2%, against a long-term norm of 1%. Perhaps there is an inflation-risk premium or an insolvency-risk premium. More plausibly, the investment boom in the US has increased the demand for capital relative to supply, pushing up the cost of debt while governments are also borrowing heavily. In time, real yields should revert to the long-term average.
If the yield on medium-term government bonds is higher than the growth rate of nominal GDP (inflation plus real growth), the ratio of debt to GDP is falling. That is the case in the US, but not in the UK, where inflation is higher and growth lower. The ratio of government debt to GDP in most developed countries rose sharply in the aftermath of the 2008 financial crisis and again during Covid. As economies recovered from Covid lockdowns, the ratio fell and the trend has been broadly flat or gently rising since.
Meanwhile, private-sector debt relative to GDP has fallen, so total debt-to-GDP ratios are either flat (US and France) or falling (UK and Germany). Rising budget deficits with no attempts at restraint would mean that debt ratios would rise remorselessly and lead, eventually, to a fiscal crisis, but that is not inevitable. As the Greek solvency crisis of 2010 showed, a crisis in one country can have a salutary effect on other threatened countries; “bond vigilantes” may not be needed.
The current level of pessimism suggests that the sell-off in bond markets is overdone. Oil and gas prices will come down, inflation will fall, capital spending in the US will tail off, real interest rates will subside, fiscal deficits will be brought under control and indebtedness relative to GDP will fall.
A straw in the wind is that the recent increase in interest rates in the US led to a fall in bond yields – reliable bullish indicator. The US Federal Reserve, but not the Bank of England, realises that raising short term rates demonstrates inflation-fighting credibility and will thereby bring down bond yields. That is positive for the housing market as US house buyers (and, increasingly, those in the UK) borrow long term.
UK ten-year gilts yielding over 5% and, especially, 30-year gilts yielding nearly 6% look good value, but with one caveat. Every period of Labour government in the last 100 years has resulted in a devaluation of sterling. Is this time really different? Charles Gave of Gavekal advocates instead 30-year Japanese bonds, yielding 4% with a seriously undervalued currency.
The ratio of Japanese government debt to GDP looks intimidating at 230% but 90% of it is domestically owned. Moreover, research co-authored by Stanford professor Hanno Lustig says that the government’s liabilities net of its massive holdings of domestic and foreign equities and bonds have fallen to just 65% of GDP. A good alternative is to buy shares: lower bond yields will boost equity markets and even the UK stock market derives 70% of its earnings from overseas, providing protection against devaluation.
This article was first published in MoneyWeek’s magazine. Enjoy exclusive early access to news, opinion and analysis from our team of financial experts with a MoneyWeek subscription.


Leave a comment