Hikma Pharmaceuticals And 2 British Biotech Stocks To Watch
October 2, 20263 Mins read3
Share
Eurozone inflation recently topped forecasts and hit a three year high, which keeps pressure on central banks and pushes investors toward areas where returns depend more on scientific progress than economic cycles. That spotlight helps British biotech stocks that pair cutting edge research with reasonable balance sheets. This article walks through three of the most interesting UK biotech shares from our screen and explains what makes each worth a closer look.
The three British biotech stocks highlighted below are just a sample from a wider search, with the full screen surfacing 3 more companies with equally compelling narratives that are not covered here. To go deeper into the opportunity set, identify your own criteria, and immediately analyze the highest conviction biotech ideas, head straight to the Biotech Stocks screener.
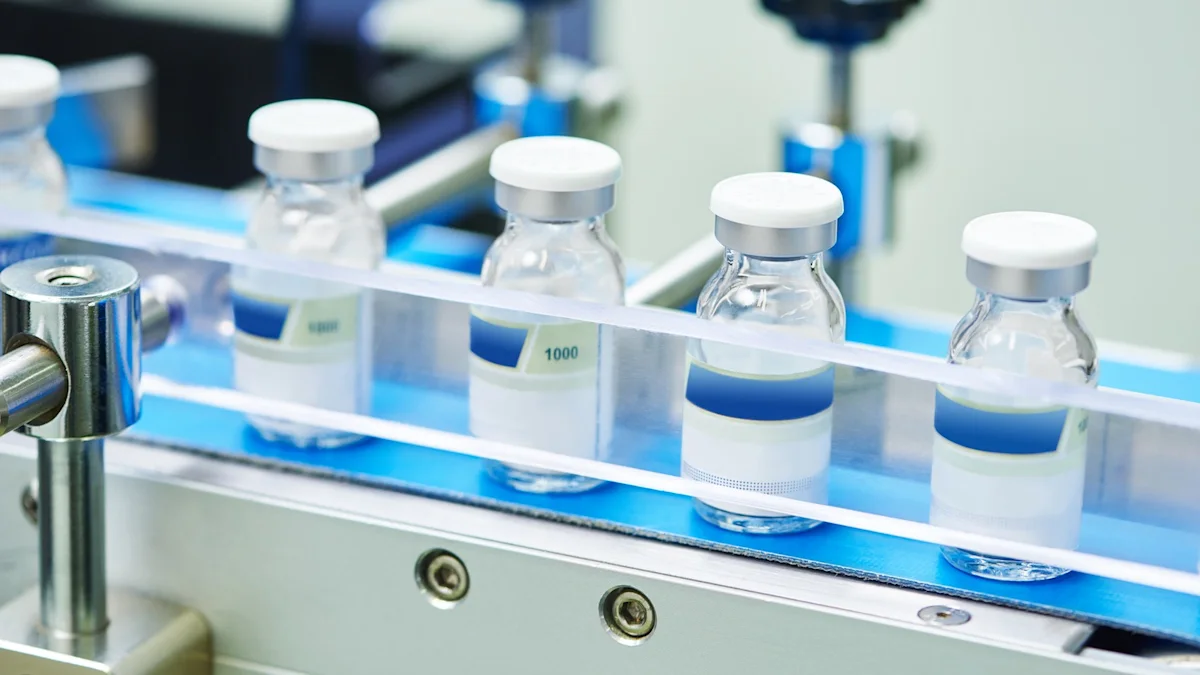
Overview: Hikma Pharmaceuticals develops and sells generic, specialty, and branded medicines, with a major focus on hospital-use injectable drugs worldwide.
Operations: Hikma generates most of its revenue from Injectables at US$1.4b, Hikma Rx at US$1.0b, and Branded products at US$914 million.
Market Cap: £3.3b
Hikma Pharmaceuticals provides biotech-linked exposure through its injectables portfolio. The wider group structure adds scale and diversification that many pure-play developers do not have.
“Hikma’s ongoing investment in expanding manufacturing capacity in the US, Europe, MENA, and new state-of-the-art facilities (for example, Bedford, Cherry Hill, Italy, North Africa, and Saudi Arabia) positions the company to capitalize on rising global demand for pharmaceuticals driven by demographic and healthcare trends.”
The key issue now is how one unresolved pressure on Hikma Pharmaceuticals ultimately shapes the balance between volume growth and profit margins.
That margin question sits at the centre of the Hikma story, and the full narrative for Hikma Pharmaceuticals unpacks how capacity, pricing, and pipeline could be quietly reshaping the upside.
LSE:HIK Revenue & Expenses Breakdown as at Oct 2026
Overview: Oxford Biomedica is a gene therapy-focused CDMO that uses its LentiVector and viral-vector platforms to manufacture vectors for biotech partners.
Operations: Oxford Biomedica mainly earns from Manufacturing Services at £88 million and Development Services at £60 million, with most income coming from US clients.
Market Cap: £616 million
Oxford Biomedica fits this Biotech Stocks screen because its LentiVector and viral-vector CDMO work ties revenue directly to gene therapy progress.
“The company’s development and manufacturing capabilities expansion into AAV and other vector types diversify their revenue streams, reducing dependency on any single vector type and potentially enhancing overall earnings and EBITDA margins.”
The key question is what happens if a bottleneck between signed vector contracts and recognised revenue lasts longer than today’s forecasts.
If that bottleneck is the real swing factor, the full narrative for Oxford Biomedica shows how contract timing, capacity build out, and gene therapy momentum could still accelerate Oxford Biomedica’s story.
LSE:OXB Earnings & Revenue Growth as at Oct 2026
Overview: Genus runs a genomics-driven animal genetics business, supplying improved cattle and pig breeding stock, semen, and embryos to farmers worldwide.
Operations: Genus PIC generates £355.8 million and Genus ABS £299.8 million, with North America the largest region at £256.6 million.
Market Cap: £1.4b
Genus gives this biotech screen a different flavour, since its genetics work applies biotech tools to livestock herds rather than human drugs. This matters if you want exposure to gene editing and breeding science that is already plugged into everyday food production.
“Rapid shifts towards plant-based diets and alternative proteins present a structural threat to Genus’s long-term addressable market, creating the risk that demand for animal genetics will stagnate or decline, placing persistent pressure on revenue growth, especially if adoption of synthetic or cell-based proteins accelerates.”
The real investment tension is what happens if one unseen pressure on Genus’s pricing power and volume mix starts to bite at the same time.
If that squeeze on Genus’s pricing power really builds, the full narrative for Genus shows where herd genetics, capital intensity and protein shifts could still be quietly compounding.
LSE:GNS Earnings & Revenue Growth as at Oct 2026
Seeking Fresh Alternatives Beyond Biotech?
Fresh ideas move first. The best breakouts and momentum shifts are often identified by early screens while they are still under the radar, so act now.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.



Leave a comment