Equities: Growth Reclaims the Lead
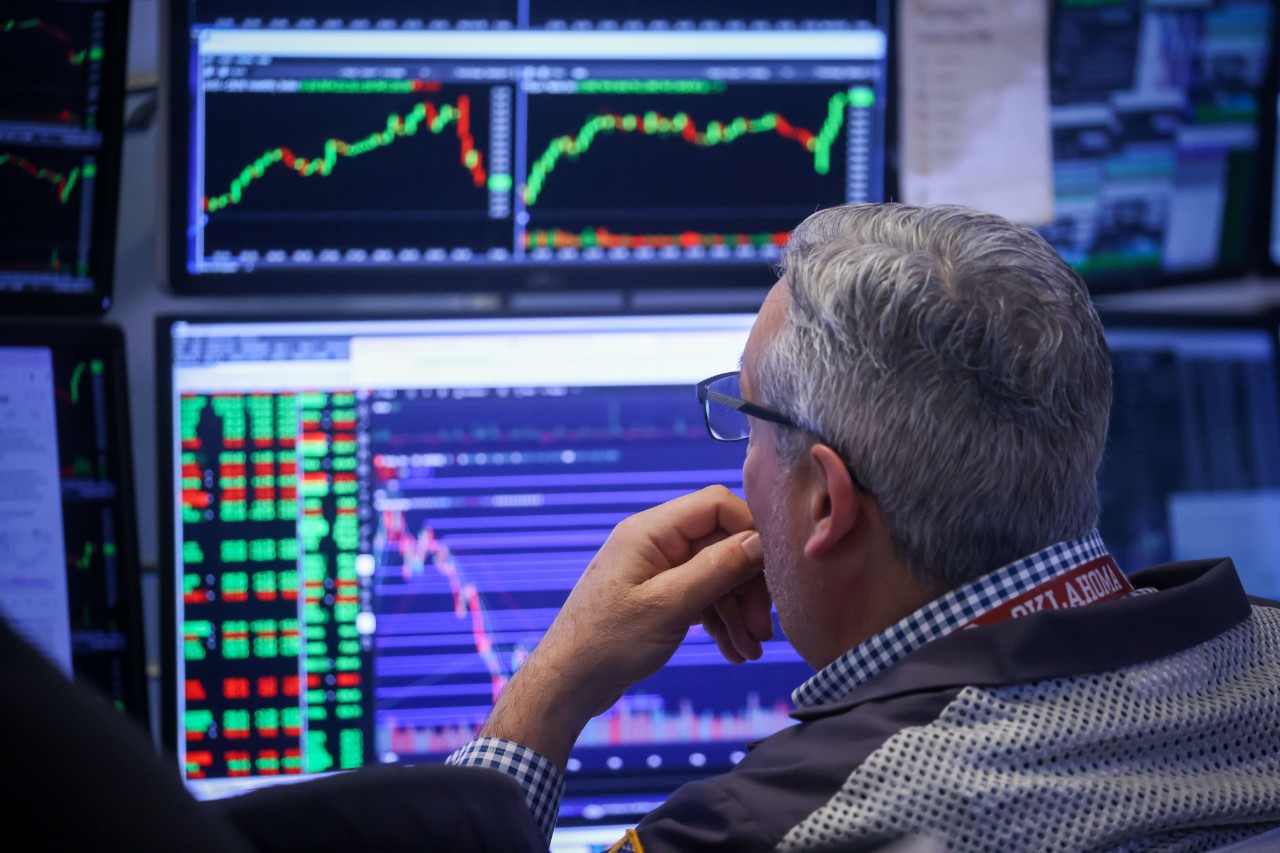
The defining feature of the month was the recovery in the AI and technology names that had sold off in July. Semiconductors, which had fallen around 25% from mid-June to late July, stabilised and rebounded, and software and hyperscaler shares resumed their advance. The result was a clean reversal of July’s rotation, with growth reasserting leadership over value across the board.
US equities led the developed world. The S&P 500 rose 2.7% and the Nasdaq-100 gained 4.2%, their strongest August performance since 2021, with the Nasdaq snapping two consecutive months of losses. The market reached a fresh all-time high early in the month before easing back, but still finished comfortably above its July close. Strong second-quarter earnings provided the fundamental backdrop, with the vast majority of S&P 500 companies beating expectations.
The UK told the opposite story to July. The FTSE 100 slipped around 0.4% over the month, held back by the very characteristics that had helped it the month before. With growth back in favour, the index’s low technology weighting and heavy tilt towards energy, banks and other value sectors became a relative drag rather than a support. Continental Europe was broadly flat, with the STOXX Europe 600 up around 0.2%, sitting once again between the UK and the US.
Emerging markets recovered as the semiconductor complex healed. The technology-heavy Asian markets that had borne the brunt of July’s sell-off were among August’s stronger performers, with South Korea and Taiwan benefiting from renewed demand for AI memory. Japan was firmer too, with the Nikkei 225 gaining around 4% as technology names recovered. The clear message of the month was that appetite for the AI theme shaken in July, had returned.
Fixed Income: Yields Keep Climbing
Bonds remained under pressure. Long dated government bond yields ground higher across developed markets through August, driven by sticky inflation risk, elevated energy prices, heavy government borrowing and a growing wall of AI-linked corporate debt adding to supply. Yields did retreat late in the month after the US Treasury announced it would at least double its long-dated buyback operations, but the broader direction of travel stayed upward.
The pressure at the long end was as much about fiscal supply and inflation expectations as about the near-term policy rate. With the Middle East conflict keeping the inflation outlook uncertain, markets remained reluctant to price meaningful rate cuts, and the higher-for-longer narrative that had taken hold only firmed. Emerging market debt also outperformed, as the US dollar softened against some of the major emerging market currencies.
Japan’s government bonds were the poorest performers (in local currency terms). The 10-year Japanese Government Bond yield rose to a multi-decade high of almost 3% as a result of a looser fiscal backdrop and inflation rising again.


Leave a comment